White label dropshipping suppliers in 2026 are shifting from “cheap and cheerful” to brand-first
White label dropshipping suppliers in 2026 are no longer a niche tool for side hustles. They are becoming the infrastructure layer for a new kind of consumer brand, one that launches fast, tests demand in real time, and scales without owning factories or warehouses. And in the middle of that shift sits one category that keeps punching above its weight: skincare.
The latest supplier roundups and platform positioning make the direction of travel pretty clear. A 2026 shortlist of “best white label dropshipping suppliers” places SelfNamed as “Best for Natural Skincare”, alongside broader fulfilment players like HyperSKU and niche specialists like Supliful, Printful, and Dripshipper. The message is blunt: generic product stores are struggling to stand out, and suppliers that can support branding, compliance, and automated fulfilment are the ones winning attention. That is not exactly groundbreaking, but it is a big deal for anyone trying to build a defensible ecommerce business.
At the same time, marketplaces that track private label manufacturing interest, such as Keychain’s directory of soda manufacturers, show how brand builders are researching production partners at scale, with entries displaying how often manufacturers are “researched by brands” in a given week. That kind of visibility is part of the story too. The private label economy is becoming more searchable, more comparable, and frankly more competitive.
The 2026 development: supplier rankings and platform messaging put white label branding at the centre
The immediate news development is the way 2026 supplier guidance frames the market. In the 2026 list of the “10 Best White Label Dropshipping Suppliers”, the editorial premise is that “generic product stores don’t cut it anymore” and that merchants need suppliers that support brand identity “from one start” (their phrasing). The shortlist spans general sourcing and automation (HyperSKU), supplements (Supliful), print on demand (Printful), coffee (Dripshipper), jewellery (ShineOn), and multiple beauty options including SelfNamed, Blanka, Jubilee, and viaGlamour. The list also provides a quick comparison table with ratings, for example HyperSKU at 4.7/5.0 and SelfNamed at 4.7/5.0, and it highlights pricing models, including “Free” for some suppliers and monthly tiers for others.
What stands out is not the existence of a list. Lists are everywhere. It is the way the list treats white label as the default route to differentiation, not an optional add-on. It explicitly calls out custom branding, automated order syncing, quality control, and warehouse fulfilment as core requirements for “brand-focused stores”. In other words, the supplier is no longer just a logistics partner. It is part of the brand’s operating system.
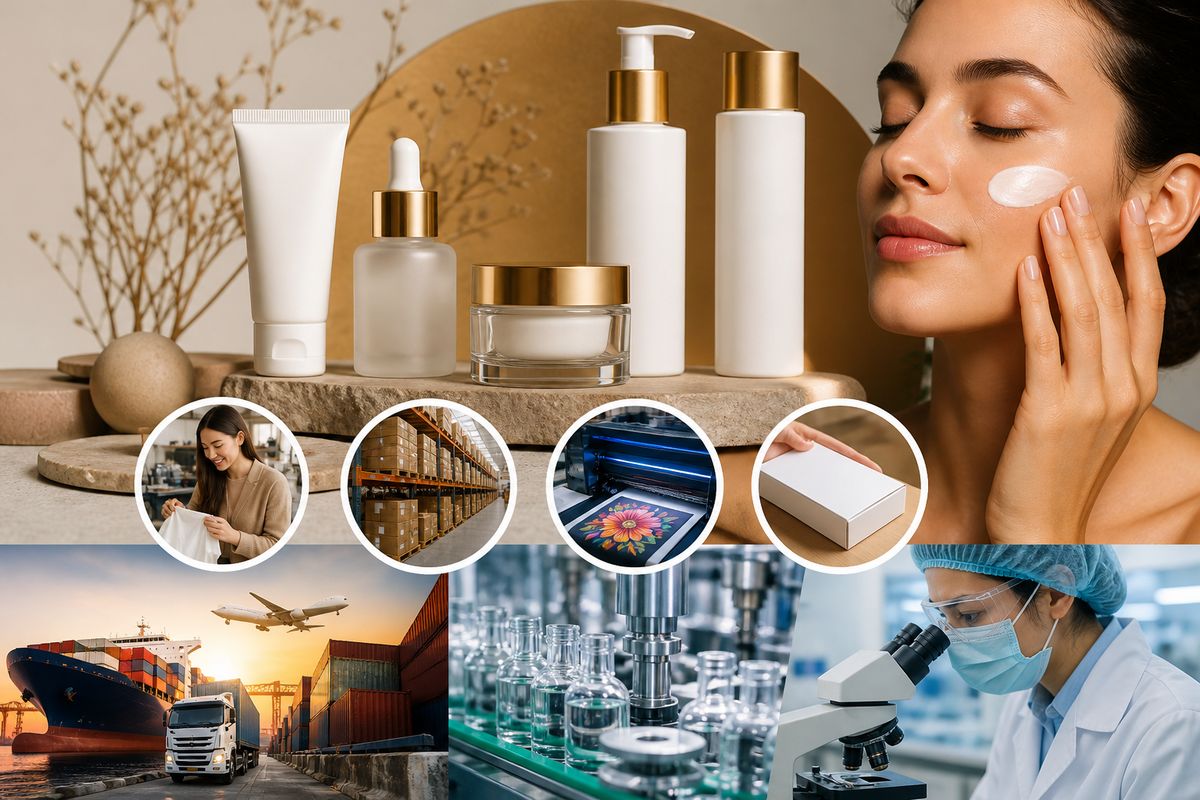
Skincare, meanwhile, is presented as a category where white label can be unusually “production-ready”. SelfNamed’s own positioning leans hard into speed and risk reduction: it describes white labelling as selling products under a brand name without owning a factory, formula, or facility, with a supplier handling manufacturing, packaging, and fulfilment. It also emphasises “no minimum order quantities”, the ability to order a single unit to test, and compliance coverage across the EU, UK, and USA. That combination is catnip for founders who want to move quickly without stepping on a regulatory rake.
Why skincare is the flagship category for white label dropshipping suppliers in 2026
Skincare is not just popular. It is structurally well suited to white label. Products are repeat-purchase by nature, brand storytelling matters, and customers often buy into routines rather than one-off items. That means a supplier that can offer a coherent catalogue of cleansers, serums, moisturisers, masks, and mists can help a new brand look “complete” from day one, rather than like a random assortment of products.
SelfNamed’s catalogue positioning is built around that idea of a ready-made range. It describes “natural and organic skincare formulas” across multiple product types, and it highlights botanical extracts such as rose, chamomile, and calendula in cleansers, plus “high-performance actives” in lightweight formats. It also calls out more specific product concepts, including “10% lactic acid serums” and alcohol-free formulas built around hyaluronic acid and botanical extracts. The source material does not provide clinical claims or performance data, and it would be irresponsible to imply them. But it does show how suppliers package product development into marketable, consumer-friendly themes.
Then there is compliance, which is where skincare gets serious. SelfNamed states that its products are “Fully compliant in the EU (CPNP-notified), UK, and USA (FDA-registered)”, and that it “handle[s] the paperwork”. It also references Good Manufacturing Practice, stating its production facility meets the international standard for cosmetics GMP, and it positions its formulas as “COSMOS-certified”. For founders, that is not a nice-to-have. It is the difference between launching confidently and spending months in regulatory limbo.
Key players and models: SelfNamed, HyperSKU, Printful, and the wider supplier stack
The 2026 supplier shortlist usefully illustrates the different “flavours” of white label. HyperSKU is framed as a broad starting point for stores that want agent sourcing, quality control, custom packaging, warehouse fulfilment, and automated order syncing, with no monthly subscription fee. That matters because many founders do not start with a product category in mind. They start with a business model, then they need a supplier that can operationalise it.
SelfNamed, by contrast, is positioned as category-specialist infrastructure for clean beauty. It offers “no MOQ” ordering, sample sets, and a “Design Studio” that lets users add logos, brand colours, and label designs, either via templates or uploaded artwork. It also states that it ships from EU and US fulfilment centres and can dispatch directly to customers or to the brand. The implication is that the supplier is not just making products. It is enabling a workflow that looks and feels like a modern ecommerce stack, with integrations mentioned in the supplier roundup, including Shopify and WooCommerce.
Other suppliers in the 2026 list show how fragmented, and how mature, the ecosystem has become. Printful represents print on demand, where branding is applied to apparel and accessories rather than consumables. Supliful is positioned around supplements with “FDA-compliant products” and a native Shopify app for automated fulfilment. Dripshipper focuses on coffee with custom bags and app-based automation. ShineOn focuses on jewellery gifts with built-in branding. The point is simple: white label is no longer one market. It is a set of category-specific supply chains, each with its own constraints, margins, and customer expectations.
Private label manufacturing goes mainstream: what Keychain’s soda directory signals
Skincare and dropshipping get the headlines because they are accessible. But the broader private label trend is visible in manufacturing directories that make supplier discovery easier. Keychain’s page on “The 13 Best Soda Private & White Label Manufacturers” reads like a window into how brands now shop for production partners. Entries show locations (for example Colorado, Wisconsin, Florida), employee ranges (from 1 to 10 employees up to 10,001+), and founding years (including long-established manufacturers founded in the 1800s and early 1900s, alongside newer entrants founded in the 2010s and 2020s).
Most telling is the behavioural data surfaced on the page, such as manufacturers being “Researched by brands” thousands of times in a week. The source material includes examples like “Researched by brands 6486 times this week” and “Researched by brands 5429 times this week”. Keychain also states it is “100% free for brands to use, no subscription required.” None of this is a market size statistic, and it does not prove conversion into contracts. But it does show intent at scale. Brands are actively searching, comparing, and initiating conversations about MOQs and product categories, including light beer and ready-to-drink cocktails, based on user notes included on the page.
For the white label dropshipping world, this matters because it normalises the idea that manufacturing is discoverable and negotiable. Historically, production relationships were opaque, relationship-driven, and slow to establish. Directories and platforms make them legible. And once production becomes legible, it becomes competitive. That pushes suppliers to differentiate through speed, compliance support, design tooling, and fulfilment reliability, not just unit cost.
Industry analysis: why “no MOQ” and compliance are now strategic weapons
The most commercially important phrase in the skincare source material is “no minimum order quantities”. In a world where paid social costs fluctuate, marketplaces change their rules, and consumer demand can turn on a sixpence, inventory risk is the silent killer. No MOQ flips the risk profile. It allows founders to validate positioning, creative, and pricing with minimal capital tied up in stock. And it changes how brand building happens: more testing, more iteration, less “bet the farm”.
But no MOQ is only half the story. Compliance is the other half, and it is where many would-be beauty founders get stuck. SelfNamed’s claims of EU CPNP notification, UK compliance, and US FDA registration, plus GMP production and COSMOS certification, are positioned as part of a managed service. That is significant because regulatory competence is not evenly distributed among new entrants. When a supplier productises compliance, it lowers the barrier to entry. It also raises the baseline expectation across the market. Competitors have to match it, or explain why they cannot.
There is a trade-off, of course. White label can compress differentiation if too many brands sell similar formulas with different labels. That is why suppliers increasingly offer a ladder: start with catalogue products, then move to private label development “for enterprise brands ready to go beyond the catalog”, as SelfNamed puts it. The strategic play is to use white label as a launchpad, then invest in formulation, packaging innovation, or community-led brand equity once product-market fit is proven. Fair enough, that is how many modern brands are built now, whether founders admit it or not.
Historical context: from private label supermarket shelves to platform-driven brand creation
Private label is not new. Supermarkets have sold own-brand goods for decades, and contract manufacturing has long powered everything from soft drinks to cosmetics. What changes in the mid-2020s is the interface. Instead of procurement teams and trade shows, founders increasingly start with a web platform, a catalogue, and a design tool. They can order samples, test demand, and connect fulfilment to an online store without ever visiting a factory.
The supplier roundup format itself is part of this evolution. It reflects a market where founders expect plug-and-play integrations, transparent pricing, and fast onboarding. The 2026 list explicitly frames automation and store integrations as selection criteria. That is a shift from the older model where manufacturing capability was the primary differentiator. Now, the differentiator is operational convenience plus brand control.
And the manufacturing directory model, as seen in Keychain’s soda page, adds another layer. It turns supplier discovery into a searchable dataset, complete with signals of popularity and activity. Again, it does not guarantee quality. But it does change behaviour. When brands can see that thousands of others are researching a manufacturer, it creates social proof and competitive pressure. The supply chain becomes a marketplace, not a back office.
What This Means For You
For founders and ecommerce operators, the practical takeaway is that supplier choice is now a brand decision, not just an operations decision. If a supplier can support no MOQ testing, provide compliant documentation, and offer design tooling that produces shelf-ready packaging, it reduces time-to-market dramatically. That is especially true in regulated categories like skincare, where mistakes are expensive and reputationally damaging. The smart move is to treat supplier onboarding like hiring a core team member: check what they handle, what they do not, and where liability sits.
For established brands, the opportunity is speed without dilution. White label can be used to launch limited runs, seasonal drops, or market-specific variations without retooling internal production. But it only works if the brand keeps control of positioning, creative, and customer experience. The risk is ending up with a product that looks like everyone else’s, because it is. The mitigation is to differentiate through packaging design, bundling, education content, and a clear routine-based merchandising strategy, rather than relying on the formula alone.
And for anyone exploring categories beyond beauty, the broader lesson from Keychain’s manufacturing directory is that private label sourcing is becoming more transparent and more competitive. That is good news, but it also means due diligence matters more than ever. Popularity signals like “researched by brands” show interest, not capability. So the action is straightforward: shortlist suppliers, ask direct questions about MOQs, lead times, quality control, and compliance, then run small pilots before committing to scale. In 2026, the winners are not the people who move fastest. They are the people who test fastest, learn fastest, and build a brand that can outlast a supplier catalogue refresh.
Closing thoughts: the white label era is growing up, and skincare is showing the playbook
White label dropshipping suppliers in 2026 are increasingly judged on their ability to help brands look legitimate from day one. That means compliance support, quality assurance, fulfilment reliability, and design tooling, all wrapped in a workflow that integrates with ecommerce platforms. The supplier roundup ecosystem reinforces that shift by rewarding platforms that make branding operationally easy.
Skincare is the clearest example because the stakes are high and the repeat-purchase dynamics are strong. SelfNamed’s positioning around COSMOS-certified, production-ready formulas, no MOQ ordering, and EU, UK, and US compliance support shows what founders now expect as standard. Meanwhile, manufacturing directories like Keychain’s soda list show that private label sourcing is becoming more visible and more data-driven across categories.
The next phase is where it gets interesting. As more brands launch on similar foundations, differentiation moves up the stack: community, education, customer experience, and product strategy that goes beyond a label swap. That is the real work. But at least the infrastructure is catching up. And for many founders, that is the difference between an idea staying in a notebook and becoming a business with real customers.
Read more: SelfNamed’s white label skincare overview is available at https://www.selfnamed.com/en/white-label-skincare. The 2026 supplier shortlist discussed above appears at https://dodropshipping.com/best-white-label-dropshipping-suppliers/. Keychain’s private and white label soda manufacturer directory is at https://www.keychain.com/manufacturer/private-label-soda.