Starting an online clothing store in 2026 is suddenly a lot more practical
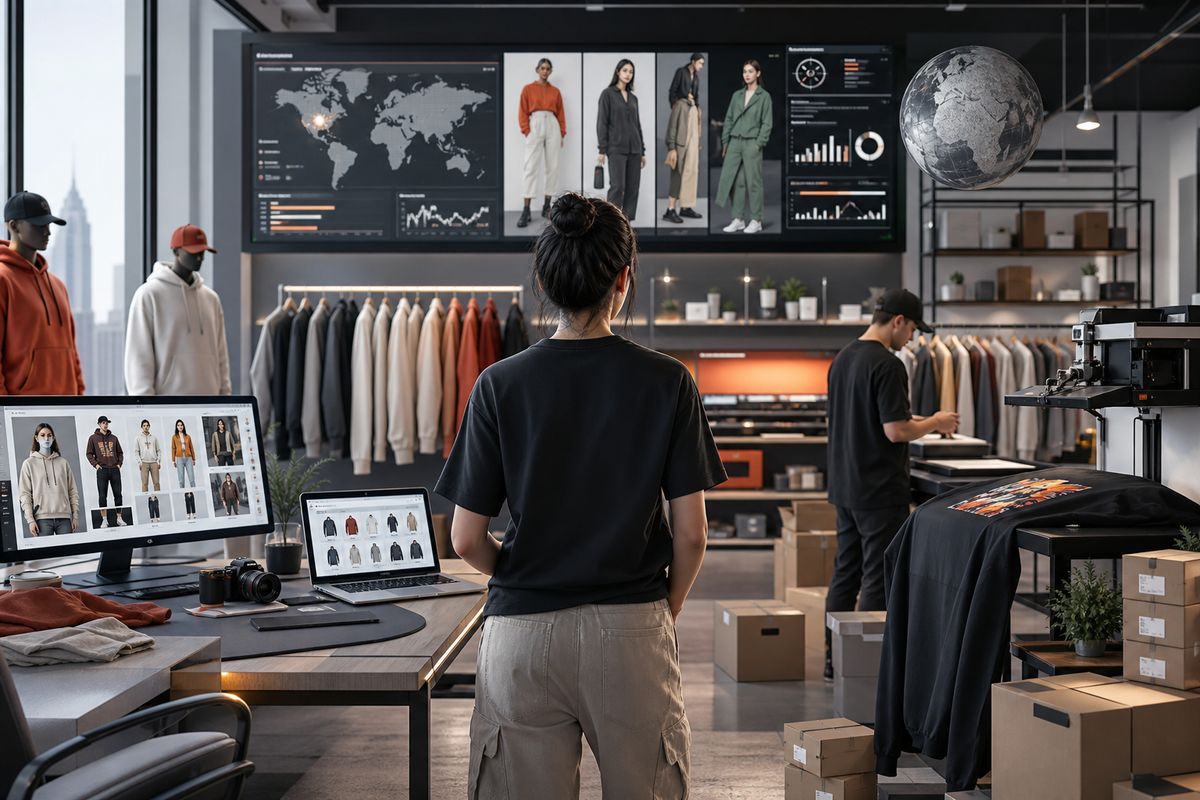
Starting an online clothing store in 2026 no longer looks like a high-risk punt that requires a garage full of stock and a scary cash outlay. The latest wave of how-to guidance from print-on-demand platforms and the continued push from dropshipping providers points to the same underlying shift: the operational heavy lifting is being productised. Inventory, fulfilment, even product photography and listings are increasingly “handled”, leaving founders to focus on brand, demand, and distribution.
Three developments sit at the centre of this story. First, Printful publishes an updated 2026 playbook for launching an online clothing store in eight steps, explicitly positioning print on demand (POD) as a low-upfront route to market and highlighting the growing role of social platforms in product discovery. Second, Printify reinforces the same direction of travel with a seven-step guide to starting a clothing brand, emphasising market research, business model choice, and the unglamorous but vital discipline of ordering samples. Third, My Online Fashion Store (MOFS) continues to market a “new dropship program” built around fast US fulfilment from Los Angeles, automated inventory sync, and a catalogue of 10,000+ styles.
None of this is exactly groundbreaking in isolation. But taken together, it signals something bigger: the barriers to entry in online fashion keep falling, while the bar for differentiation keeps rising. And that is the real headline for 2026.
The 2026 playbook: what the new guidance actually says
Printful’s 2026 guide frames the opportunity with a set of market indicators that, while broad, are hard to ignore. It states that global fashion ecommerce sales are on track to surpass $1.2 trillion by 2030, that the apparel market is valued at $1.8 trillion in 2025 and is heading towards $2.5 trillion by 2033, and that social platforms now drive over 60% of product discovery, ahead of Google search. It also cites a forecast for the US print-on-demand market to grow at a 24.4% CAGR through 2030. These figures are presented in Printful’s own material and reflect the narrative it is building: demand is expanding, and distribution is shifting towards social-first discovery.
From a practical standpoint, Printful’s advice is a structured “eight steps” approach: choose a business model (POD, dropshipping, or wholesale), use customer research to select products, design with tools or freelancers, set up a store with intuitive navigation and SEO fundamentals, then promote via social, email, and influencers, scaling with product data rather than guesswork. The guide is published at https://www.printful.com/blog/the-basics-of-starting-an-online-clothing-store.
Printify’s seven-step guide covers similar ground but leans harder into brand fundamentals and operational discipline. It argues founders do not need a fashion degree or a massive budget, but they do need clarity on who they are selling to, a deliberate business model choice, and a plan. It also calls out a simple quality-control truth: ordering samples is the easiest way to avoid quality issues before they reach customers. That guidance appears at https://printify.com/blog/how-to-start-a-clothing-brand/.
MOFS, meanwhile, is not publishing an editorial guide so much as selling a packaged operating model. Its “new dropship program” claims 1 to 2 day fulfilment from a Los Angeles warehouse, automated inventory sync, and access to 10,000+ US-based styles. It also states that, since launch, its dropship members have sold over $6,100,000 worth of merchandise. The programme details are at https://www.myonlinefashionstore.com/pages/new-dropship-program.
Print on demand and dropshipping are converging, but the trade-offs still bite
In 2026, POD and dropshipping increasingly look like two variations of the same promise: “sell first, pay later, do not touch inventory”. But the mechanics matter, and founders who gloss over them tend to learn the hard way.
Printful describes POD in straightforward terms: a seller uploads designs, selects products such as t-shirts or hoodies, and lists them in an online store. When an order comes in, Printful prints, packs, and ships directly to the customer. The upside is clear: zero upfront investment in inventory, no storage or fulfilment to manage, and the ability to test designs quickly. The downside is equally clear: lower profit margins than bulk production and limited control over product quality, unboxing, and delivery speed. That “limited control” line is doing a lot of work, because it goes to the heart of brand building in fashion.
Printify’s framing is similar. It calls POD the “leanest, fastest way” to launch, with low startup costs and simplified logistics, but notes the trade-off: limited control over materials and packaging. It positions POD as ideal for testing ideas, launching limited drops, and starting with minimal risk, while a traditional model (holding inventory, working directly with suppliers, cut-and-sew) offers more control and higher profit potential but requires upfront investment and introduces inventory risk.
MOFS’s dropshipping pitch lands in a slightly different place. It emphasises speed and convenience: 10,000+ items, professional photos and descriptions, automated stock sync, and fulfilment in 1 to 2 days from Los Angeles. It also claims sellers keep “100% of the profit”, which in practice means the seller sets retail pricing and pays MOFS’s wholesale and fulfilment costs. The key point is not the slogan, it is the operational model: a ready-made catalogue and logistics layer that makes it possible to launch quickly, especially for boutique-style stores that prioritise breadth of assortment over custom design.
Background: the platforms shaping how an online clothing store in 2026 gets built
Printful and Printify sit in the same broad category, but they are not identical in how founders experience them. Both are part of the wider infrastructure that has grown up around creator-led commerce, where the “factory” is an API and the storefront is a Shopify theme. Their guides reflect that worldview: the founder is a marketer and product curator first, and an operator second.
Printful’s editorial approach is notably store-building oriented. It talks about niche selection, product research, store navigation, pricing, and SEO, then pushes promotion through social media, email, and influencers. It also explicitly recommends tools and channels for research, including Google Trends, Semrush, Etsy, Instagram, TikTok, and Reddit communities such as r/streetwear and r/femalefashionadvice. The point is not that these tools are new. It is that the “research stack” for fashion founders is now mainstream and largely free at the entry level.
Printify’s guidance reads more like a brand-building checklist. It starts with the target audience, then competition analysis and gap spotting. It encourages founders to look beyond demographics into spending habits, fit preferences, shopping channels, and price expectations. And it stresses samples as a quality gate. That is a subtle but important difference: in a world where anyone can launch, quality and consistency become competitive advantages, not nice-to-haves.
MOFS represents the other side of the coin: a dropship catalogue model aimed at boutique operators who want speed, variety, and minimal friction. It highlights integrations with platforms such as Shopify and Wix, offers a free plan with limits, and paid plans starting at $9 per month. It also promotes operational features that matter when a store starts to scale: returns support with prepaid labels and a 30-day return window, plus “real human support” via US-based phone, chat, and email. Whether those features are decisive depends on the founder’s strategy, but the direction is clear: dropshipping providers are competing on service levels, not just product lists.
Industry analysis: why 2026 feels like a tipping point for online fashion
The most important shift is not that it is easier to launch. It has been easier for years. The shift is that the default distribution model is changing, and the sources here say it plainly. Printful states that TikTok, Instagram, and YouTube drive over 60% of product discovery, ahead of Google search. That single line has big implications for how an online clothing store in 2026 should be structured, merchandised, and marketed.
Search-led ecommerce rewards breadth, long-tail SEO, and incremental optimisation. Social-led commerce rewards speed, creative iteration, and a strong point of view. It also rewards products that “read” instantly on video: bold graphics, distinctive silhouettes, clear subculture cues, and obvious before-and-after value. That is why both Printful and Printify keep returning to niche clarity and audience definition. In social-first discovery, a brand that tries to please everyone often ends up pleasing no one.
At the same time, the operational layer is becoming commoditised. POD providers handle printing and fulfilment. Dropship programmes handle inventory sync, product photography, and shipping. That is great for founders, but it creates a new problem: if everyone has access to similar tools, the differentiators move up the stack. Brand story, community, customer experience, and product development discipline become the battleground. And yes, that includes the boring bits: sample testing, returns policies, and customer support responsiveness (the stuff that rarely goes viral, but quietly determines whether a store survives).
There is also a margin reality that founders cannot wish away. Printful openly notes that POD can mean lower profit margins than bulk or wholesale production. Dropshipping models can face similar pressure, especially when paid social costs rise or when competitors sell near-identical catalogue items. The strategic response is usually one of three paths: charge more by building a brand people actually care about, reduce costs through smarter operations and pricing discipline, or move towards more proprietary product over time. Many founders will do all three, in stages.
Historical context: from “side hustle stores” to infrastructure-driven brands
Online fashion has always had low barriers to entry compared with traditional retail, but the early era still demanded operational competence. Founders had to source stock, manage storage, handle shipping, and deal with returns manually. The rise of marketplace platforms helped with traffic, but often at the cost of brand control and margin.
POD and modern dropshipping changed that equation by separating brand-building from fulfilment. Printful’s description of POD is essentially the industrialisation of custom merchandise: upload design, list product, fulfil automatically. Printify’s framing goes further by positioning POD as a legitimate route not just for online-only brands but also for samples, pop-ups, and local sales. That matters because it blurs the line between “internet brand” and “real brand”. The operational model is no longer a signal of legitimacy. The customer experience is.
MOFS’s programme reflects a parallel evolution in dropshipping. Earlier dropshipping models were often criticised for long shipping times, inconsistent quality, and weak customer service. MOFS leans hard into the opposite: US-based inventory, 1 to 2 day fulfilment from Los Angeles, returns support, and live assistance. It is an attempt to make dropshipping feel more like a conventional retail operation, just without the inventory risk. Whether every provider can deliver that consistently is a separate question, but the competitive direction is unmistakable.
And then there is the cultural shift. Printful notes that younger shoppers are moving away from established brands towards labels with better products, stronger values, or a more personal shopping experience. The source does not quantify that trend beyond the statement itself, but it aligns with what many founders observe in the market: consumers increasingly buy identity and affiliation, not just fabric and stitching. That is why niche ideas like “bold graphic tees for indie horror fans” or “minimalist streetwear for tech bros” are not just cute examples. They are a commercial strategy.
What This Means For You
For anyone considering starting an online clothing store in 2026, the practical takeaway is blunt: the easiest part is launching. The hard part is choosing a model that matches the founder’s strengths and then building a brand that can survive copycats. POD is compelling when speed, low upfront cost, and design iteration matter most. Dropshipping is compelling when assortment breadth and fast time-to-market matter more than custom product. Traditional inventory models become compelling when the brand needs control over materials, fit, packaging, and margin, and when the founder is ready to manage complexity.
But the decision should not be ideological. It should be tactical. A sensible approach many founders take is to start with POD to validate demand and creative direction, then introduce more controlled production for bestsellers once the audience is proven. Printify’s emphasis on ordering samples is a useful discipline here, even for POD. If a founder cannot be bothered to check quality before selling, the market will punish them quickly, usually via returns, negative reviews, and rising customer acquisition costs.
And marketing needs a rethink. If social platforms drive over 60% of product discovery, as Printful states, then the store’s product strategy should be built for social. That means clear niche positioning, strong visuals, and rapid creative testing. It also means the website must do its job once the click arrives: intuitive navigation, smart pricing, and basic SEO hygiene, all of which Printful calls out. The founder does not need to become an SEO technician overnight, fair enough. But they do need to treat product pages, collections, and site structure as revenue infrastructure, not decoration.
How to choose between POD, dropshipping, and traditional in 2026
There is no universal “best” model, and both Printful and Printify are explicit about that. The right choice depends on the founder’s constraints and ambitions: budget, time, appetite for operational work, and the kind of brand they want to build.
POD suits founders who want to test designs quickly, run limited drops, and avoid inventory risk. It is also a strong fit for creators with an existing audience, because the brand distribution engine already exists. The trade-off is margin and control. If the brand promise depends on premium materials, distinctive fits, or a luxury unboxing experience, POD can feel restrictive unless the provider’s product range and branding options align with that promise.
Dropshipping, as MOFS presents it, suits boutique operators who want to curate trends and launch fast using a large catalogue with ready-made assets. The operational pitch is attractive: automated inventory sync, professional photos and descriptions, and fulfilment in 1 to 2 days from Los Angeles. But founders should be realistic about differentiation. If multiple stores can list the same items with the same photos, the competitive edge must come from curation, pricing strategy, customer experience, and marketing execution.
Traditional models suit founders who want deeper control and are prepared to invest. Printify notes the upside: stronger brand identity and higher profit potential. The downside is the obvious one: upfront investment and inventory risk. In 2026, traditional production is often best viewed as a second phase, not a starting point, unless the founder already has capital, supply chain access, or a proven customer base.
Closing thoughts: the opportunity is real, but so is the competition
The 2026 narrative from Printful, Printify, and MOFS is consistent: it is easier than ever to start, and the infrastructure is there to remove many of the old blockers. Fashion ecommerce is growing, POD is forecast to expand rapidly in the US, and social platforms increasingly dominate discovery. That combination creates genuine opportunity for new entrants, especially those with a clear niche and the discipline to execute.
But the same forces that make launching easy also make competition brutal. When fulfilment, inventory, and even product listings are commoditised, the winners are the brands that understand their audience, test relentlessly, and build trust through quality and service. The playbook is not mysterious. It is just work. And in 2026, that is the difference between a store that gets a few sales and a brand that actually lasts.
For readers weighing the leap, the most useful mindset is to treat the first launch as a learning system. Validate demand with low-risk models, measure what sells, order samples, tighten the offer, and only then scale. The tools are ready. The market is big. The rest comes down to choices, and follow-through.